

14/10/2026

Share:
14/10/2026
Share:

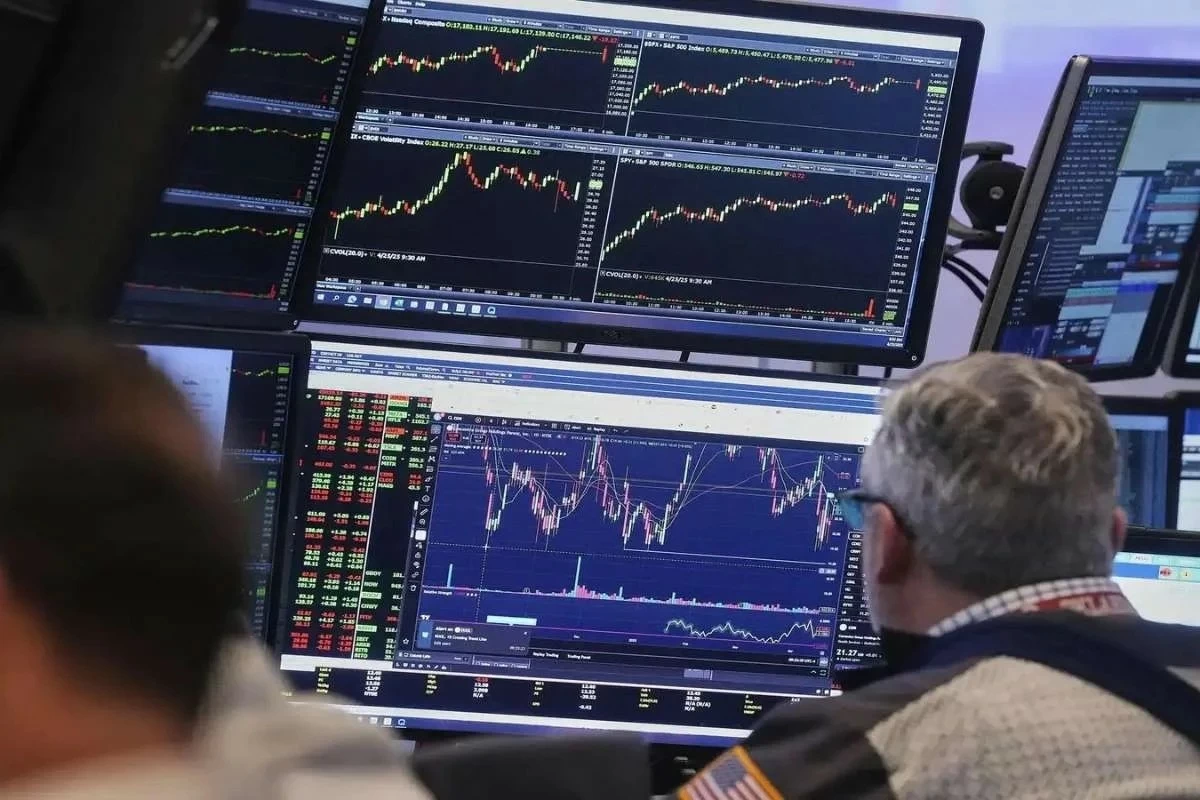
KUWAIT CITY, Oct 14: Wall Street is entering a critical earnings season with an unusual combination of strong corporate profitability, elevated borrowing costs and increasingly demanding equity valuations.
The central question is no longer whether American companies can generate earnings growth. Instead, investors are assessing whether that growth is sufficiently resilient to justify current share prices in an environment where government bonds offer increasingly attractive returns.
The latest results from major U.S. banks provide an early indication of the underlying strength of corporate America.
On October 13, several leading Wall Street institutions reported higher third-quarter profits, supported by resilient consumer activity, investment banking operations and continued corporate investment.
JPMorgan Chase reported quarterly net income of $15.3 billion, compared with $14.4 billion a year earlier. However, its earnings per share fell short of analysts' expectations, illustrating how even substantial profits may disappoint investors when market expectations are particularly demanding.
Citigroup reported a 40% increase in quarterly profit, while Wells Fargo and Goldman Sachs also delivered higher earnings.
The results suggest that important parts of the American financial system remain resilient despite the challenges created by elevated interest rates and persistent inflation.
Nevertheless, strong bank earnings do not necessarily guarantee a favorable environment for the broader equity market.
Higher Treasury yields have increased the returns available from fixed-income investments, creating stronger competition for capital that might otherwise flow into equities.
This matters particularly for companies trading at elevated valuation multiples, where investors are effectively paying today for profits expected to materialize several years into the future.
When bond yields rise, the present value of those anticipated earnings declines, potentially placing pressure on share prices even when companies continue reporting revenue growth.
The issue has become increasingly relevant as the benchmark 10-year U.S. Treasury yield recently reached its highest level in approximately 24 years.
Meanwhile, analysts surveyed by LSEG expected third-quarter earnings across the S&P 500 to increase by more than 30% from a year earlier, highlighting the exceptionally strong profit growth already embedded in market expectations.
“The headline earnings number can make corporate America look stronger across the board than it really is. FactSet found that analysts raised third-quarter earnings estimates for the S&P 500 by 1.4% during the quarter, yet cut estimates in eight of its eleven sectors. That distinction matters: aggregate optimism can coexist with deteriorating expectations across much of the market. I would place more weight on whether earnings upgrades spread to more sectors. A broader improvement would give investors firmer grounds for confidence than another strong result from a handful of leaders.” Van Ha Trinh, Financial Markets Strategist at Exness.
Another important consideration is the relationship between corporate profitability and consumer spending.
Major banks have indicated that American consumers continue meeting their financial obligations, although executives have warned that prolonged inflation and elevated borrowing costs could eventually weaken household finances.
Higher mortgage rates, financing expenses and energy costs may gradually influence purchasing decisions, corporate investment and credit demand.
For equity investors, this creates a distinction between companies capable of maintaining profitability through operational efficiency and those whose earnings depend heavily on favorable financing conditions.
Technology investment introduces another dimension.
Artificial intelligence infrastructure continues attracting substantial corporate spending, supporting demand across technology, industrial equipment and related services.
However, the scale of these investments also increases scrutiny of future returns.
Companies may demonstrate impressive revenue expansion while simultaneously facing pressure on free cash flow because of rising capital expenditure.
Consequently, investors are likely to place greater emphasis on earnings quality, operating margins, balance-sheet strength and the ability to convert accounting profits into sustainable cash generation.
The emerging earnings season therefore represents more than a routine assessment of quarterly corporate performance.
It offers an opportunity to evaluate whether profitability across the American economy can withstand higher financing costs without requiring a significant adjustment in equity valuations.
In an environment characterized by expensive capital and heightened expectations, the distinction between earnings growth and economically sustainable earnings growth is becoming increasingly important.