

05/11/2026

Share:
05/11/2026
Share:
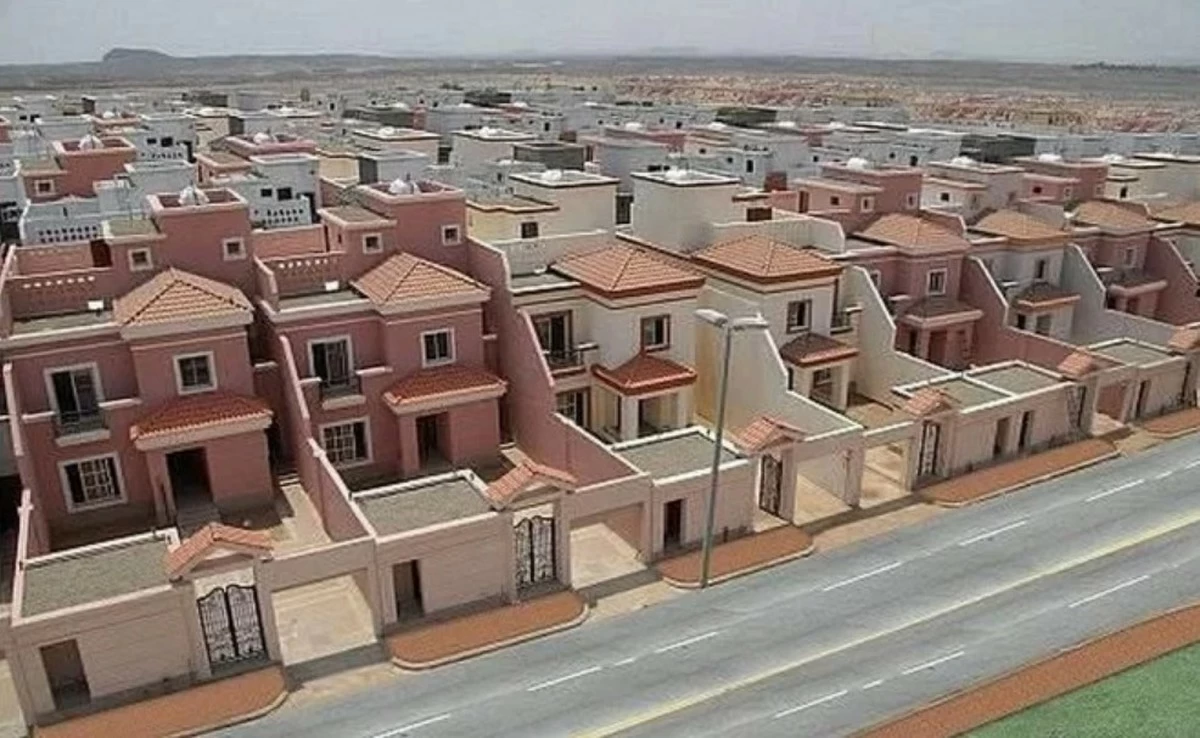

KUWAIT CITY, Nov 5: The Ministry of Finance confirmed that Decree- Law No. 114/2026 on real estate financing for individuals who are eligible for housing assistance enables qualified citizens to obtain real estate financing from local banks and finance or investment firms under the supervision of the Central Bank of Kuwait, reports Al-Seyassah daily. This is an alternative to the house construction and purchase loans offered by Kuwait Credit Bank (KCB).
The law shall take effect once its executive regulations are published in the official gazette, ‘Kuwait Al-Youm’. In a press statement on Thursday, the ministry disclosed that this is a vital development in housing finance due to the additional financing options for citizens and the involvement of the banking and financial sectors in the housing market. The executive regulations are expected to be released within six months after the publication of the decree-law in the official gazette, along with the rules and guidelines that will be laid down by the Central Bank. Ahmed Al-Ansari, who chairs the committee formed for this purpose through a ministerial decree, indicated that such financing is limited to two purposes -- acquiring a residential unit from real estate developers endorsed by the Public Authority for Housing Welfare (PAHW) or constructing a house on a plot allocated by the government. He said the decree-law does not cover other uses, such as property expansion, renovation, purchase from entities other than the approved real estate developers, and construction on privately owned land. He revealed that this financing has two complementary components.
The first is subsidized financing, for which the state covers the interest. It is an alternative rather than a replacement for the construction and purchase loans offered by KCB, such that citizens have the right to choose between the two. Second is additional non-subsidized financing for those purchasing residential units from real estate developers. This is provided by financing institutions as per their credit terms, while state support is solely for the subsidized portion. Al-Ansari explained that subsidized financing is granted on a one-time basis to individuals who meet the criteria stipulated in the real estate loan regulations of KCB for the purpose of purchasing or constructing a home, provided they have not previously benefited from state housing assistance, including loans from KCB. He stated that this decree-law complements Law No. 118/2023 on the establishment and development of residential cities or districts by linking the expansion of housing supply with the provision of financial tools for citizens to access it.
Meanwhile, committee member Faisal Al- Muzaini indicated that this financing will be paid in equal monthly installments for a period not exceeding 25 years from the date the fund is disbursed. Beneficiaries may be granted a grace period— included in the total term, during which the payment of the principal is deferred. This applies to those who purchase properties from real estate developers or construct a house on an allocated plot. In such instances, the beneficiary remains responsible for the interest accrued during the grace period. Beneficiaries have the right to make full or partial early payments, in which interest on the portion of the debt that has been paid shall be waived.
On defaults, Al-Muzaini pointed out the decree law mandates financing entities to issue a formal notice to the beneficiary, as per the procedures that will be stated in the executive regulations. It also permits the rescheduling of financing for a period not exceeding five years, in accordance with the Central Bank’s directives. The regulations must provide clear guidelines for banks and financing entities to follow in the event of a default, ensuring that it does not result in the foreclosure or immediate sale of the property. In the event of a default, KCB -- acting on behalf of the state -- is obligated to pay the remaining balance of the subsidized fund to the financing entity. CBK retains the right to seek recourse against the beneficiary for the amount paid, hence, the beneficiary remains fully liable for his obligations.
The property remains mortgaged as security for the fulfillment of financing obligations until they are fully settled. The property cannot be disposed of without approval from KCB and the financing entity. Any individual or entity receiving the property must qualify for housing assistance, must not have a history of obtaining real estate financing, and must shoulder the existing responsibilities of the beneficiary. KCB or any other organization appointed by the relevant minister is allowed to acquire real estate financing portfolios, fully or partially, from the original lenders. These portfolios can be securitized and made available to investors, in accordance with the regulations of the Central Bank and the Capital Markets Authority (CMA). This approach aims to ensure the necessary liquidity for ongoing financing, while assisting in the diversification of investment options and development of local financial markets.