

04/11/2026

Share:
04/11/2026
Share:
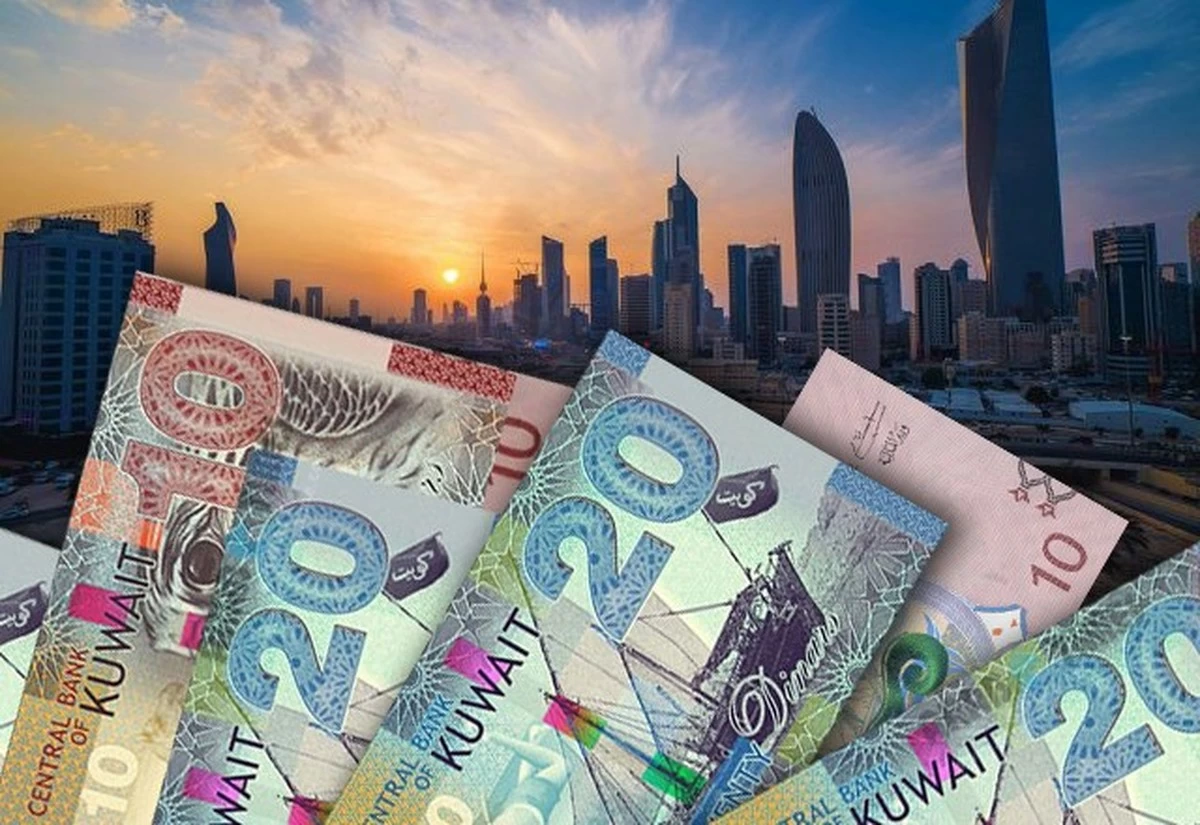

KUWAIT CITY, Nov 4: The Central Bank of Kuwait has instructed local banks to introduce stricter monitoring of salary transactions involving private-sector employees earning monthly salaries of KD 300 or less, requiring two-factor authentication for withdrawals, transfers and payments of KD 25 or more.
The new measures will take effect on December 31, 2026, as part of efforts to protect workers' wages and prevent employers from recording fictitious salary payments or forcing employees to return money after it has been deposited into their bank accounts.
Under the instructions, banks must apply two-factor authentication to every withdrawal, transfer or payment transaction of KD 25 or more from accounts designated for salary payments, including transactions conducted through associated payment methods and different banking channels.
The salary deposit itself will not require additional authentication.
An employee's eligibility for the additional security measures will be determined according to the latest monthly salary information recorded by the bank, rather than the account balance or the amount of an individual transfer. The classification must be updated whenever the employee's salary changes.
Banks have also been instructed to verify the employee's identity and consent for each transaction through two separate verification employees from different categories. Simply authenticating when logging into a banking application or other banking channel will not be sufficient.
Before a transaction is approved, the employee must be shown its type, amount and beneficiary.
The Central Bank has further stressed that authentication methods must be personally linked to the employee. Banks must directly verify the accuracy of customers' contact details when they are registered, changed or retrieved, rather than relying solely on information supplied by employers.
Banks must also provide secure alternative authentication methods for employees who do not own smartphones or cannot use banking applications.
Six months of transactions subject to review
The instructions make clear that successful two-factor authentication does not necessarily rule out wage manipulation or situations in which workers are pressured to return their salaries.
Banks therefore remain responsible for monitoring suspicious activity, examining transactions and reporting potential violations, including suspicious transactions involving amounts below KD 25.
When suspicious indicators are detected, banks must review the employee's banking transactions covering the preceding six months, compare them with the employee's usual financial behaviour and examine possible links with the employer or related parties. The findings must be properly documented.
However, the Central Bank has stressed that banks must not delay salary deposits or restrict employees from using their own money solely because of a suspicion, unless there is a legal basis for doing so.
Monitoring employer violations and protecting workers' rights remain within the jurisdiction of the Public Authority for Manpower and other competent authorities.
When do salary transactions raise suspicion?
The Central Bank's instructions identify several indicators that could point to fictitious salary payments or possible pressure on employees to return their wages.
These include:
- Direct indicators: Employees returning their salaries to employers or affiliated parties without an apparent legitimate reason, employers retaining workers' bank cards or PINs, and documented complaints that employees were forced to return their wages.
- Large withdrawals: Withdrawing or transferring 80 percent or more of an employee's salary within 72 hours in at least two of the previous three salary cycles.
- Transfers to employers: Transferring 50 percent or more of the salary to the employer or an affiliated party within 72 hours.
- Group transaction patterns: Similar transactions involving five employees or 20 percent of an establishment's workforce, whichever is lower.
- Repeated cash withdrawals: Patterns involving groups of employees repeatedly withdrawing their salaries from the same ATM.
- Joint accounts: Salary transfers to joint accounts linked to the employer.
The instructions classify cases according to risk. High-risk cases involve strong evidence, while medium-risk cases involve repeated suspicious behaviour supported by additional indicators. Low-risk cases involve a single suspicious indicator.
Strict investigation and reporting deadlines
Banks are required to conduct an initial review within two days. Where sufficient grounds for suspicion are established, the matter must be reported by the end of that day.
A further three-day monitoring period is provided to complete a detailed investigation, while urgent cases must be reported immediately.
The Central Bank has also directed banks to complete their technical and operational preparations before December 31 and submit monthly reports on monitoring and investigation results by the fifth working day of the following month.
Banks must establish internal supervisory policies and subject them to annual internal audits. Financial institutions that fail to comply with the instructions may face supervisory measures determined by the Central Bank.
The new requirements complement the Kuwait Wage Payment System (KWPS), launched on September 28 to address fictitious wage payments by ensuring that salaries are actually received by their rightful beneficiaries.
The measures are intended to ensure that private-sector employees not only have their salaries recorded as paid but also receive their wages and retain the freedom to use their money without pressure from employers.
The Central Bank has clarified that withdrawing an entire salary in cash, by itself, is not sufficient evidence of fictitious wage payment or a violation. The guidelines are intended to identify suspicious patterns and protect workers, not to prohibit employees from withdrawing or spending their own wages.