

14/09/2026

Share:
14/09/2026
Share:
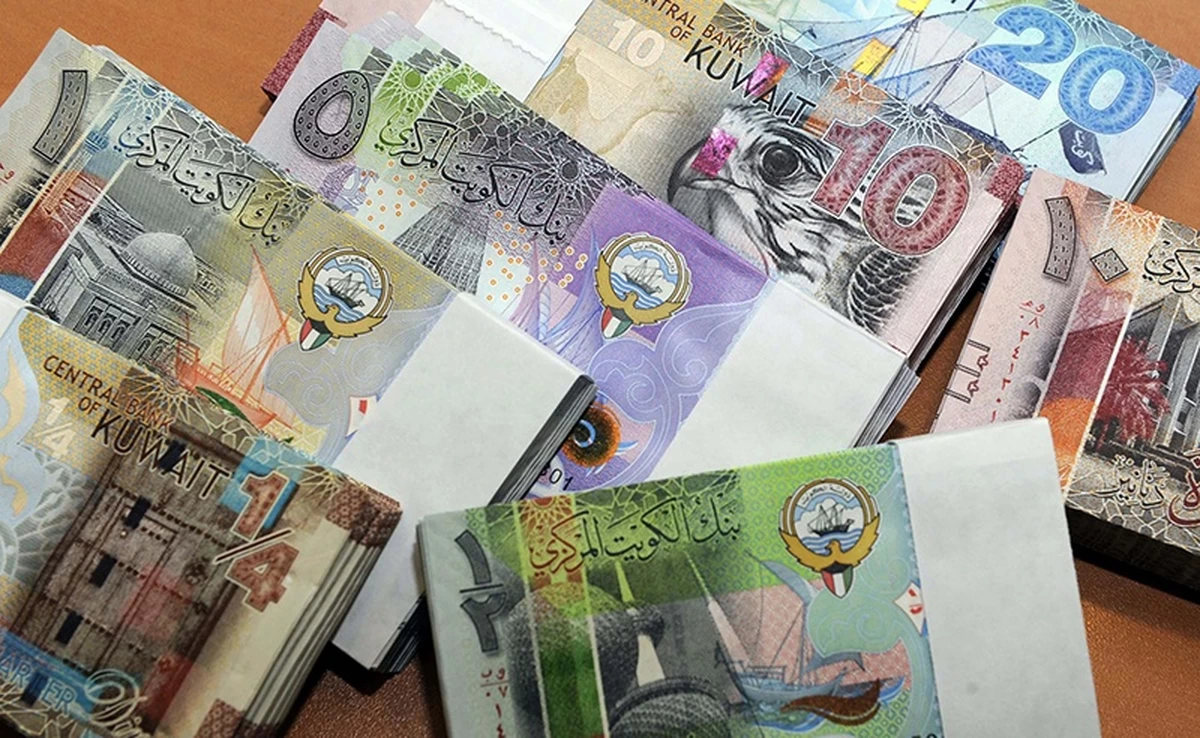

KUWAIT CITY, Sept 14: Local banks are tightening lending criteria for expatriates amid growing concerns over job security, Kuwaitization plans and the termination of expat workers, while continuing to extend credit selectively to customers with stable employment, strong salaries and sufficient guarantees.
The shift marks a move from broader lending policies toward a more selective approach aimed at reducing banks’ exposure to potential defaults resulting from job losses or contract terminations.
Banking sector sources said government positions subject to Kuwaitization, jobs considered surplus and occupations facing possible restructuring are coming under greater scrutiny. Teachers in government schools are among those being assessed, particularly employees in specializations affected by plans to address surplus staffing.
The concerns have also extended to employees of cooperative societies and public benefit organizations, some of whom are considered more exposed to possible contract termination or restructuring.
However, the tighter approach does not amount to a complete suspension of lending to expatriates. Banks continue to finance eligible non-Kuwaiti customers, particularly specialists and employees in professions considered relatively secure.
Stable jobs preferredBanks continue to favor doctors, engineers, healthcare professionals, technicians and employees working in technology and artificial intelligence, as well as teachers in specializations not considered at risk of Kuwaitization in the medium term.
Longer service with a reputable employer is also viewed positively. A stable job, a strong salary certificate, good credit history and sufficient end-of-service benefits can improve a customer’s eligibility for financing.
Employees with a substantial period of service — particularly around 10 years or more — are considered lower-risk customers because of their accumulated end-of-service benefits. Banks may take these benefits into account when determining the amount of financing that can be granted.
Newly appointed employees and those with lower educational qualifications are facing greater scrutiny, with financing for such customers generally subject to stricter conditions and lower credit limits.
Financing limitsUnder current lending criteria, a Kuwaiti or expatriate who meets the applicable regulatory and banking requirements can obtain combined personal consumer and housing financing of up to KD 95,000, subject to the applicable interest rate and repayment conditions.
For a financing amount of KD 95,000, the customer would need a salary of around KD 2,750, with an estimated monthly installment of KD 1,100, representing 40 percent of net salary.
For a KD 25,000 loan, the required salary is around KD 1,225, with an estimated monthly installment of KD 490.
The exact amount approved varies from customer to customer depending on salary, repayment capacity, employment status and other credit criteria.
Employer mattersBanks also place importance on the financial strength and reliability of the customer’s employer.
Employees of companies listed on the Kuwait Stock Exchange or those already approved within a bank’s systems may receive more favorable consideration, particularly where the bank has a clear record of the company’s salary payments and financial standing.
For companies that are not listed or have no established banking relationship with the lender, banks may assess their reputation, size, market presence and operational stability.
Some banks also require minimum salary levels, with thresholds varying between institutions.
Another factor is whether an employer follows clear governance and transparency practices, including notifying the bank of changes to employees’ salaries or employment status and transferring end-of-service benefits to the lending bank if employment is terminated before the loan is fully repaid.
Kuwaitization affects loan decisionsThe expected Kuwaitization of certain professions is increasingly becoming a factor in banks’ credit decisions.
Judges, for example, continue to receive high credit ratings, but with the planned Kuwaitization of the judicial system by the end of 2030, loan repayment periods may be limited in line with the expected replacement timeline.
Banks are therefore increasingly assessing not only a customer’s current salary and credit history, but also the expected stability of the job throughout the loan repayment period.
Platinum CustomersAt the same time, expatriates classified as high-value or “platinum” customers continue to receive preferential treatment from banks.
These customers typically have substantial deposits, strong financial positions, shares or other assets that can serve as guarantees, as well as significant end-of-service benefits. Such customers may qualify for higher financing limits, competitive interest rates and specialized banking products.
Banks continue to compete for this segment because of its strong financial profile and lower perceived credit risk.
What banks look forAmong the key factors supporting loan approval for expatriates are:
- Stable employment
- Strong and consistent salary
- Good credit history
- Sufficient end-of-service benefits
- Reputable and financially stable employer
- Deposits, shares or other acceptable guarantees
The overall trend, according to banking sector sources, is therefore not a blanket restriction on expatriate lending, but a move toward selective financing based increasingly on job security, income stability and the strength of the customer’s guarantees.