

19/10/2026

Share:
19/10/2026
Share:

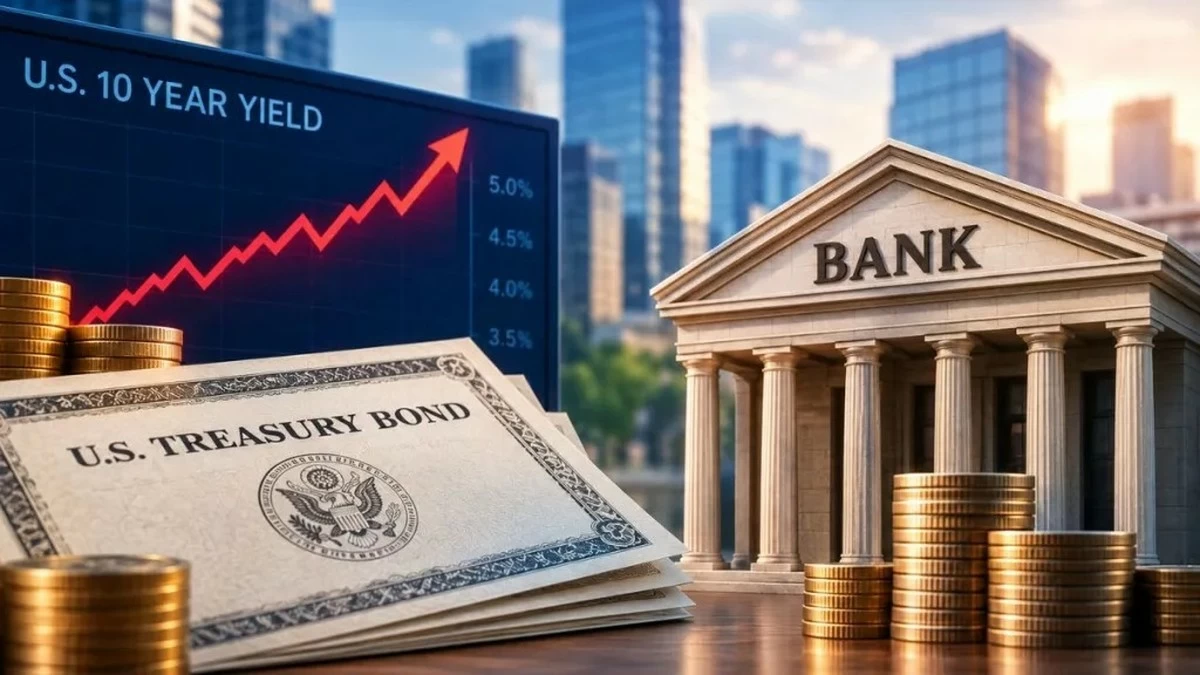
KUWAIT CITY, Oct 19: Global bond markets are entering a new phase in which elevated yields are no longer being treated as a temporary consequence of monetary tightening. Instead, investors are confronting the possibility that higher borrowing costs could become a more persistent feature of the financial landscape, with implications extending from government finances and mortgages to equities, currencies and emerging-market capital flows.
The shift has been particularly visible in the United States. Benchmark 10-year Treasury yields surged by more than 50 basis points in September and reached 5.3645%, their highest level in roughly 24 years, as higher energy prices revived inflation concerns and investors reassessed the outlook for monetary policy. Long-dated bonds experienced similar pressure, with the global selloff pushing borrowing costs sharply higher across several major economies.
Although Treasury yields subsequently retreated from their peaks, the adjustment has not removed the underlying debate. By October 16, the 10-year yield had moved back toward 5% as investors sought safety during a sharp correction in technology shares. The reversal illustrated how government bonds can still attract defensive demand during periods of market stress, even as their longer-term outlook remains complicated by inflation, fiscal deficits and heavy debt issuance.
The implications extend well beyond bond portfolios. Higher sovereign yields establish a more demanding benchmark against which other investments are valued. When investors can obtain relatively attractive returns from government debt, equities and corporate bonds must offer stronger prospective returns to compensate for additional risk. This is particularly important for highly valued companies whose share prices depend heavily on profits expected far into the future.
Inki Cho, Senior Financial Markets Strategist at Exness, sees high yields as 'an expected development. This is a time of reckoning for the Fed, and its response vis-à-vis any rate hikes in the coming months will be fundamental. The lack of forward guidance on policy moves should not be taken as a telling sign of a shaky monetary policy, but rather a cautionary stance while cross-market volatility remains the key underlying theme.
Another key underlying theme is the slowing pace of AI earnings. For example, price-to-earnings ratios on the S&P 500 are high, but not extremely high, pointing to a slowdown in earnings across the sector. The question is whether the AI sector will continue to attract capital as quickly as it has since the start of the year and whether this growth is sustainable long-term.
Lastly, fiscal sustainability across the US and major G7 economies, including the UK, Japan, Germany, and France, is gradually becoming an imminent near-term risk, further dampening investor sentiment.
Housing is another area where the impact is becoming increasingly visible. The rise in Treasury yields has pushed US 30-year mortgage rates to around 7.4%, close to a three-year high. Higher financing costs discourage refinancing and make home purchases more expensive, potentially weakening activity in a sector that is highly sensitive to changes in interest rates.
Governments face an equally significant challenge. The International Monetary Fund estimates that average 10-year government bond yields across the Group of Seven increased by more than one percentage point between February and September, reaching their highest level in nearly two decades. At the same time, global public debt is projected to exceed 100% of global GDP by 2030.
That combination creates a difficult fiscal equation. As existing debt matures and governments refinance at higher rates, interest expenses consume a larger share of public revenues. The IMF projects the average effective cost of government financing to rise from 2.3% in 2021 to 3.7% by 2031. This could reduce governments’ capacity to fund infrastructure, social programmes and other priorities while increasing pressure for more disciplined fiscal policies.
The effects are also crossing borders. Asian bond markets recorded $8.21 billion in net foreign outflows during September, the largest monthly withdrawal since March 2020. Rising US yields contributed to the shift by increasing the relative attractiveness of dollar-denominated assets and encouraging investors to reassess exposure to emerging markets.
For currency markets, this creates another layer of complexity. Higher US yields can support the dollar by attracting international capital, but that relationship is not automatic. During the latest technology-driven market correction, Treasury bonds attracted safe-haven flows while the dollar weakened against several major currencies, demonstrating that investors may distinguish between demand for US fixed income and demand for the US currency itself.
The next stage for bond markets will therefore depend on more than central-bank decisions. Inflation, energy prices, fiscal borrowing requirements, economic growth and investor appetite for government debt are increasingly interacting to determine long-term yields.
For global markets, the central issue is whether elevated yields represent a temporary adjustment or a lasting change in the cost of capital. If borrowing costs remain structurally higher, their influence will extend far beyond government bonds, reshaping corporate financing, equity valuations, housing markets, currencies and international capital flows. In that environment, the bond market may increasingly become the mechanism through which changes in inflation and fiscal expectations are transmitted across the global economy.