

20/10/2026

Share:
20/10/2026
Share:

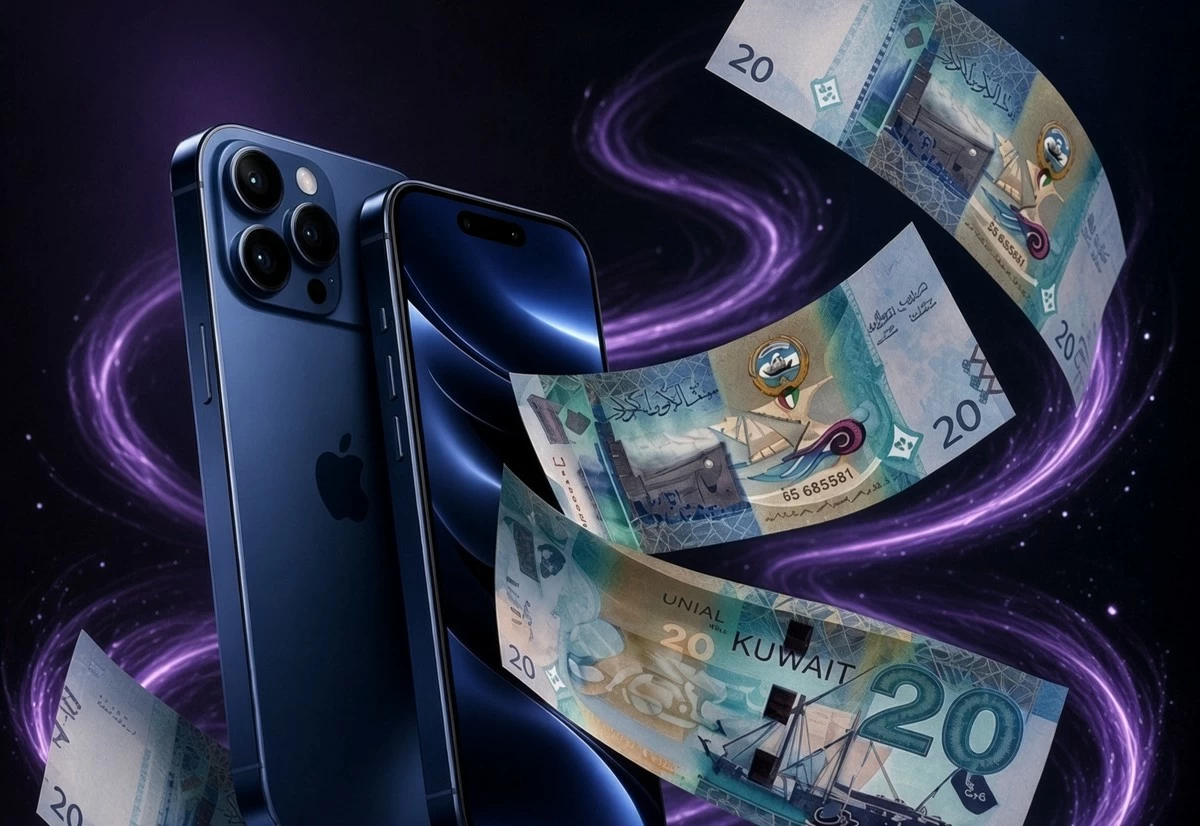
They pointed out that anyone participating in this system could be implicated in serious legal offenses, particularly money laundering and facilitation of fictitious credit. Economist and former financial advisor to the Ministry of Finance Mohammad Ramadan clarified that while ‘cash out’ may not have an immediate impact on the national economy, the need to pursue and eliminate such practices is increasingly urgent as they spread. He said this is concerning because the ‘cash out’ of high-end smartphones and electronic devices disrupts local market pricing. He explained that when an individual purchases a device on an installment plan and immediately sells it to a retail outlet for a fraction of its real value to obtain instant cash, that retailer can then sell the same device at a price lower than the official market rate. “This undermines the true value of goods, creates unfair competition, distorts domestic trade, and negatively affects the profits of companies operating in full compliance with the law,” he added.
He indicated that the ongoing pursuits and decisive actions led by the Ministry of Interior — in cooperation with the Ministry of Commerce and Industry and other relevant state authorities — to combat the ‘cash out’ practice are not isolated efforts, as they are an integral part of the intensive national campaign to root out money laundering and sever channels of illicit financing. He emphasized that the total eradication of ‘cash out’ is a vital step toward protecting the financial integrity of Kuwait. He asserted that this practice is a concerning manifestation of money laundering, involving the movement of liquidity from unknown sources through commercial fronts and transactions that appear legal on the surface, but conceal criminal activity. He stated that such practices tarnish the reputation of the local commercial sector, hence, the need for coordinated regulatory vigilance to block fictitious accounts and crack down on intermediaries and those who violate the law. Economic advisor Abdullah Al-Ghareeb said this is not a recent development in the country, as it has already spread and entrenched in the local market for several years, evolving through various innovative methods to circumvent the regulatory framework. He explained that the core of this practice is converting electronic devices obtained on credit into quick cash. He disclosed this is facilitated through complex networks of intermediaries and unlicensed merchants operating ‘shadow banking’.
He said these actors exploit individuals who are either in financial distress or seeking funds without meeting the criteria established by the Central Bank of Kuwait and other concerned authorities. He warned that such practices create a fertile environment for the growth of a shadow economy and illicit financial cycles in the country. He detailed the process, indicating that a borrower or customer visits a major telecommunications company or a large retail outlet to obtain expensive electronic devices or smartphones through monthly installment plans or deferred payment contracts, taking advantage of the credit facilities offered by these companies. “Once the individual leaves the store with the devices, he immediately heads to an unlicensed intermediary or a complicit retail shop to sell the brand-new products. These are sold at a much lower price, as much as 40 percent below the market value, to obtain instant cash. Consequently, the individual incurs a long-term debt in exchange for a sum that is exhausted within a few days, leaving the customer burdened with installment payments that exceed his financial capacity,” he elaborated. Talking about the impact of this dangerous phenomenon on the performance of banking and financial institutions, he warned that ‘cash-out’ severely damage a client’s credit profile, as the practice create an illusory inflation of an individual’s financial solvency, masking true indicators of default or repayment capacity. He stated that banks grant loans based on inaccurate and misleading credit data, leading to the rise of non-performing loans and bad debts on bank balance sheets.
He added these operations cause liquidity to leak into unregulated channels, undermine the monetary policy of the state, and hinder efforts to regulate the credit market—diverting financing away from productive economic sectors into fictitious financial channels or speculative activities that harm the national economy as a whole. Salem Al-Kandari, a lawyer specializing in money laundering cases, emphasized that the stringent regulatory measures currently being implemented by the state, which have been in place for several years, involve an unprecedented level of coordination aimed at curbing ‘cash-out’ schemes and eliminating their sources. He revealed that the penalties and enforcement measures include the permanent revocation of commercial licenses for entities found to be involved in such operations, immediate administrative closure of businesses or offices that use legitimate commercial activities as a front to facilitate these illicit ‘cash-out’ practices, and pursuing all suspicious activities, tracking funds, and identifying the intermediaries who manage these networks.
He indicated that these efforts are supported by an integrated security and regulatory cooperation involving the Ministry of Interior through its criminal investigation units, Ministry of Commerce and Industry through its oversight and consumer protection sector, and the Communications and Information Technology Regulatory Authority (CITRA). “Together, they aim to block promotional advertisements for these illicit operations and disable the telephone numbers and digital accounts used by these intermediaries, thereby, safeguarding Kuwaiti society and the national economy from this pervasive scourge,” he concluded.